The Flying Frisby - money, markets and more
647 episodes — Page 1 of 13
The AI Boom, the Debt Boom and Reality
Gold Isn’t an Investment. It’s Money | James Turk
Silver’s Brutal Reversal, and the Mine I’m Betting On
Gold Will Do Things You Can't Even Imagine | Frank Giustra
The Problem With Owning Anything
You're Poorer Than They Tell You
Trying to make sense of everything
The 2.5% Deposit Trap
They’re Coming for Your Money. Don’t Let Them Take It.
Odyssey, Bitcoin & the Three-Pinter
How to Play the Next Bitcoin Cycle
When Time Stops
The Three Financial Storms on the Horizon
The Commodity Supercycle Has Begun
Alasdair Macleod: Only A Gold Standard Can Stop The Currency Collapse
Copper Is Telling Us Something
What Actual Gold and Silver Investors Are ACTUALLY doing
Former Rothschild Banker Exposes China’s Obsession with Gold
Is the Uffington White Horse Actually a Horse? And What Is It Doing There?
Toby Baxendale: Red Tape Nation
Steve Baker: Politics in a Nutshell - Tax, Borrow, Debase the Currency
Does Britain Need A Financial Crisis To Change Course?
Is Britain Following the Venezuelan Playbook?
Metals Exploration: Is It Time to Sell?
Liv Boeree: Humanity's Big Bet
Luke Gromen: Why Gold Is About to Matter More Than Ever
The Sweetness of Doing Nothing
Brutal Summer Ahead for Gold Stocks?
Why Hasn't the Pound Crashed?
Lifetime Membership Is Ending
A Brutal Friday
Wise Up: Why I’m Still Buying Bitcoin
How AI Became My Production Company
How To Invest In Namibia
I've Outsourced My Judgement to AI. So Has Everyone Else.
Copper: The Metal AI Actually Runs On
Namibia: Africa’s Empty Frontier
Gold and Humanity
Gold Waits While Britain Cracks
The Problem with Mining Bull Markets
Constable Country, the Cracks Beneath and Opportunity
What I’m Doing With My Money Right Now (Mostly Nothing)
Namibia and the Resource Curse
Namibia: Everything on a Plate
When Other Money Fails
The Secret History of Gold Comes to America
Gold’s “Worst Month Ever” Is a Buying Opportunity
This is a free preview of a paid episode. To hear more, visit www.theflyingfrisby.comYou’ve probably heard: gold has just had the worst month in its history.Given that gold is older than the earth itself, that’s quite a long history. What headline writers actually mean, even if they don’t know it, is that: in US dollar terms, gold just had its worst month since 1971, at a stretch 1789.But the US dollar is a bogus, fiat measure, and the sooner we start using constant money as our unit of account, the more truthful the world will become. Gold hasn’t changed. It doesn’t. What has swung, violently as ever, is the price of fiat. The move looks more extreme than it is because of where the month started. Gold began March near a high, around $5,400, and then sold off hard. A thousand-dollar swing sounds a lot, but after the run we’ve just had it’s not especially surprising. Indeed I would go as far as to say it’s normal. Here is a 3 year chart of gold to put the March move in some perspective. I’ve also added a very useful indicator - the 233-day exponential moving average - in red. 233 is a Fibonacci number, and with roughly 250 trading days in a year, the 233 EMA works out as roughly the one-year average, but with the added magical quality that Fibonacci numbers often seem to have. In this case, it caught the exact bottom, as you can see.What effectively has happened is that after a long run-up gold has pulled back to the one-year average and bounced off it.What we’re seeing is normal behaviour in a secular bull market.Corrections feel violent at the time. They always do. But this is what bull markets do.My view remains unchanged. We are somewhere in the middle of a multi-year move that ultimately takes gold into the $7,000 to $10,000 range. By the way, if you’re interested in learning more about gold, the latest edition of Charlie Morris’s Atlas Pulse is out now. It remains in my view the most level-headed gold letter out there. And, best of all, it’s free. Read it here.The bigger point is not the chart, it’s the backdrop. I keep saying it, but you absolutely must own some gold in your portfolio, particularly if you are in the UK, indeed anywhere in Western Europe. We have big, big problems coming down the tracks and they are going to result in the further debasement of the national currency.Debt levels are rising, not falling. Governments are spending more, not less. The cost of servicing that debt is going up. The political incentives all point one way: more issuance, more intervention, more currency debasement.The UK is a particularly clear example. You can already see the strain in the gilt market, the pressure on public finances and the complete lack of both political will and ability to address it in any meaningful way. No party is going to fix this. The system itself is broken.There is only one way fiat money is going and it’s the same way it’s always gone.If you live in a third world country such as the UK, I urge you to own gold or silver. The pound will be further devalued, as will the euro and dollar. The bullion dealer I recommend is The Pure Gold Company. They deliver to the UK, the US, Canada and Europe. More here.Treat pullbacks like this for what they are: opportunities.If you don’t own gold, you are relying entirely on a monetary system that is under visible strain. That in itself is a bet, whether you realise it or not.Onto more positive news - or is it? Squeaky bum time in NicaraguaMy largest position, and a core holding for many readers, is Metals Exploration (MTL.L).Broker Hannam has just put a 37p price target on this 13p stock, implying roughly 3x upside. The current market cap is about £400 million.The share price has pulled back sharply after its recent run to 19p to around 12–13p, largely tracking the ups and downs of gold.The company has just issued a construction update, following a recent site visit to the main project in Nicaragua, La India, attended by major shareholders including Nick Candy. Execution is everything now, and it’s squeaky bum time.
Oil Broke the System
This is a free preview of a paid episode. To hear more, visit www.theflyingfrisby.comNever mind the dodgy mortgages, oil spiking to $150/barrel in July, 2008, just before the panic set in, was as big a cause of the Global Financial Crisis.The price rise was like a sudden, unexpected liquidity drain on the economy. The US economy is built on oil. Costs suddenly rose across every supply chain. Disposable income was sucked out of households. Corporate margins got squeezed and inflation expectations rose effectively tightening financial conditions, just as the system needed liquidity. Funding costs then rose and collateral quality deteriorated. In a system already stretched with cheap credit and thin margins, highly leveraged institutions and ordinary borrowers were simultaneously pushed over the edge. The structure was fragile and it only worked in a low energy, low rate world. Subprime may have been the trigger, but the energy shock had already destabilised the foundations.The oil price tightened financial conditions before central banks didThis is not a one-offAs Charlie Morris points out in his piece What Happened in 1974, there have been three major oil shocks - in 1973/4, 1980 and 2008.In 1973 the US was dependent on Arab nations for most of its oil, and shortly after the Egypt-Syria alliance suddenly declared war on Israel, oil-producing Arab nations imposed an embargo on any nation that supported Israel. “You can support Israel or have cheap oil, but you can’t have both,” the Saudi Arabian king had said on US TV.The oil price went from $3.50 to $10. It would eventually peak at $39.50 in 1980.I was only a little boy in the 1970s but we lived in South Kensington and I remember how many Arabs suddenly moved to the area, many of them with a great deal of money. My step-father ran a business in Belgravia selling modern Italian furniture and his clientele changed almost overnight. Hundreds of billions of dollars, previously in Western bank accounts, now made their way to the Gulf in a transfer of wealth like no other. Next came the Rolls Royces, the racehorses, the Harrods shopping sprees (indeed Harrods itself), the mansions, the public school educations, the City petro-dollar recycling trade and yes the over-priced, glitzy, Valentino furniture. London would never be the same.And what impact did those years have on bond and equity markets more generally? The 1970s were horrible, unless you were long commodities. The low reached in 1982 was so extreme that it marked one of the greatest long-term buying opportunities ever known, perhaps the greatest. While 2008 had its own consequences, not least the end of the City as a leading player in the global financial system (thanks to the regulation which followed), followed by the general decline of London.Each of these episodes follows a similar pattern: an energy shock tightens conditions, exposes leverage and forces a reset.It might not feel that way today with oil at $100, but we are still a long way from the extremes of 1974, 1980 or 2008. A lot of commentary is saying the investment world is too complacent and has not factored in what is coming.What is 2008’s $150 oil in today’s money?I’m not going to give you the CPI numbers because I consider CPI a bogus measure. Using money supply instead (M2), the equivalents look like this* 1974: $10 oil ≈ $120-150* 1980: $40 oil ≈ $360-440* 2008: $150 oil ≈ $375-450In the context of those extremes $100 oil does not look unreasonableThe sub-$60 prices with which we began this year now look extraordinarily cheap. I don’t think we are going back to them any time soon.I’m also not saying we are going to those comparable numbers above. I merely show them for context.In terms of where we are going, I think Charlie has it right when he says, “We should assume that $100 oil implies a slowdown, $150 a recession, and $200 a depression”.$200 is not impossible if this was carries on.What to do?Let’s take a quick look at how to position ourselves, and at what’s in store for gold, silver, miners and the equities markets.It was the right call to move into energy at the beginning of the year, I’m pleased to say. With such quick profits the temptation is to sell. I’m maintaining my positions.The US, especially after the Venezuala episode, is self-sufficient in hydrocarbons. Europe is not. Whose oil and gas will it be buying now that Gulf supplies are in doubt, and Russian supply is off-limits?Meanwhile, high energy prices make shale extraction profitable again.North American oil and gas comes out of this strong.
Has Gold Already Peaked?
Bull markets don’t last forever. When you’re in the throes of one, it can feel like they do. But they don’t, and at a certain point you have to sell.Gold bull markets can feel even more eternal. Not just because the metal itself is eternal, but because the story comes along that we are going back to a gold standard, or that the Great Purge, which many economists of the Austrian school say is inevitable after fifty years of fiat decadence, is finally upon us.I get that argument. But it is too neat, too deterministic. Real life is much more mucky.So today I want to consider a very important question, and I want to try and answer it honestly:Where are we in this bull market?Has gold already peaked? It’s possible. The spike to $5,600/oz at the end of January had many of the hallmarks of a blow-off top.Or perhaps $5,600 was just a mid-cycle peak, such as we saw in 2006 or 1975-76 during previous bull markets.Or is this bull market still in its infancy?I’m going to study this bull market through every lens I can think of: price, time, valuation, participation, market structure, macro context and sentiment.My bias going in is that we are mid-cycle, as I argued in my Great Forecast last week. Let’s see where I end up. 1. DurationThere have been two great gold bull markets since the end of the gold standard: 1971-1980 and 2001-2011. Both lasted nine to ten years.When did this one begin?It depends how you define it.You could take the bear-market low of $1,045 in late 2015. You could take the $1,160 retest in 2018. You could take 2019, when gold broke out of its multi-year base.Technical analysis is often in the eye of the beholder. Just like bull markets.You could even argue late 2022, when the current acceleration began.If you start in 2015, this bull market has already lasted ten years. That would put it right in line with the duration of previous cycles, and you could argue it is close to exhaustion.If you start in 2018 or 2019, there may be several years left to run.I favour 2018. Just as gold hit $250 in 1999, rallied, and then returned to roughly the same level in 2001 before the real bull market began, the 2018 low feels like the equivalent retest. Of course this is debatable.And there is always the possibility that this bull market lasts longer than previous ones.Verdict: mid- to late-cycle.2. Relative valuation vs other assetsOilWith gold at $5,200 and WTI crude around $87, it takes roughly 60 barrels of oil to buy one ounce of gold.Historically this ratio ranges between 6 and 30.The only time oil has been this cheap relative to gold was in the 2020 pandemic collapse, when oil went negative.My view: it’s not so much that gold is expensive as that oil is cheap. Plus commodities inevitably get cheaper as we get better at producing them. (As long as you don’t measure the price in fiat).Gold vs the S&P 500With the S&P around 6,765, it takes about 1.3 ounces of gold to buy one unit of the index.This ratio has been as high as 5 - at the peak of Dotcom in 2000, and the nadir of gold - and as low as 0.2 (during the depths of the 1930s and at the 1980 gold peak).Gold is therefore on the expensive side relative to equities, but not at historic extremes.This ratio could fall further if equities fall or gold rises.Gold vs US housingThe US housing market varies enormously by region - Beverely Hills is not Detroit, Miami Beach is not McDowell County - so national averages should be treated cautiously. But they still give a rough guide.We are now below the 2011 level and approaching 1980 territory in terms of how many ounces of gold buy a typical home.Pretty extreme.Overall verdict: late-cycle. Warning signal3. Institutional ownershipGold is still under-owned in institutional portfolios.Even after the recent rally, gold represents only a tiny fraction of global portfolio allocation compared with equities and bonds.Gold mining equities are even more neglected.Verdict: mid-cycle4. Central banksCentral bank buying slowed to 863 tonnes in 2025, down from record levels in 2024, but still well above the 2010-2021 average.However, the World Gold Council reported that central banks purchased only 5 tonnes in January, below the monthly average of 27 tonnes. I would not read too much into that. Much buying is reported with delays, and China in particular reveals little about its activity. The usual assumption is that central bank buying is an early or mid-cycle phenomenon. I am not entirely convinced. If the real driver of this bull market is de-dollarisation and reserve diversification amidst a wider geopolitical shift, then official buying could persist for years.Gold currently represents just under 30% of central bank reserves. The US dollar still accounts for roughly 56%.I don’t think this bull market ends until gold sits north of 50% having overtaken the dollar itself.Question: is the war in Iran going to arrest of accelerate de-dollarisation? You know the answer. Verdict: mid-cycle5. Retail participationRetail demand is growin
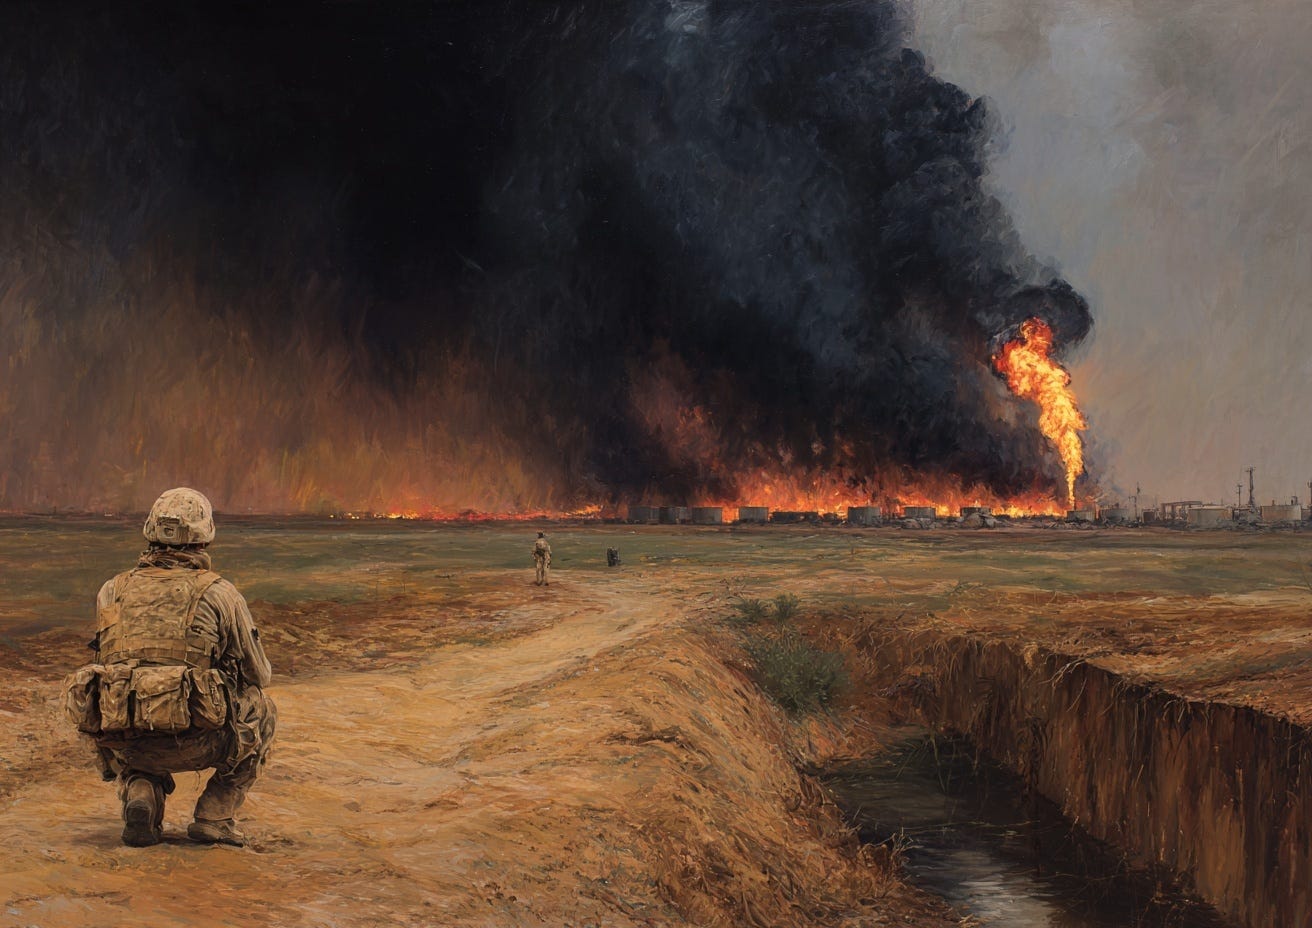
War, Oil and the Cost of Stupidity
Good Sunday to you,You’ve no doubt seen the videos of Iran’s largest oil facilities burning.How much destruction does war cause? To the environment, to wealth, to people’s lives. And governments lecture us about the environment.15% of China’s oil comes from Iran. Not any more. I bet they’re delighted.No surprise, oil futures have spiked again. WTIC has gone to $94 in weekend markets, Brent to $97.I’m glad we own oil and I’m glad we own gold. Iran meanwhile has started targeting desalination plants across the Middle East - how most neighbouring Arab nations get their water - and the probability of an early end to this conflict, despite Donald Trump already claiming the win, seems to be receding by the day.According to Polymarket, the probability of a US-Iran ceasefire by March 31 is just 24%. Even by the end of April it is just 48%. The odds are 67% that the Iranian regime will still be in power by June 30.Meanwhile, in the UK, the strategic stupidity of being dependent on overseas sources for oil, gas and coal when we have perfectly abundant supplies of our own is about to hit home in the form of yet higher energy costs. The government will no doubt blame everyone and everything but itself.UK borrowing costs are now rising faster and higher than any other European nation, which spells trouble for the housing market, business and the economy, and government finances. Ten year gilt yields are now above 4.5% and it costs more for the UK government to borrow than it does any other G7 nation, and indeed any PIIGS nation, which became such laughing stocks after the GFC.Happy days.If you live in a third world country such as the UK, I urge you to own gold or silver. The pound will be further devalued, as will the euro and dollar. The bullion dealer I recommend is The Pure Gold Company. They deliver to the UK, the US, Canada and Europe. More here.Here’s a five-year chart of gold priced in pounds, in case you were wondering what a trend looks like. There’s only one way this is going.You can look at a 10- or 20-year chart. It’s the same story.Here also for your reference is a long-term chart (since 1983) of the gold-oil ratio. You can see how cheap, historically, oil is.And that’s even after the rally of the last fortnight.What if it goes back to the top of that range?I’m glad we bought oil when we did, before this all kicked off. As always when a market moves in your direction, I now wish we’d bought more.Here is this week’s commentary, in case you missed it. Lots of forecasts for the year ahead. Take a look if you haven’t already seen it.Thank you for being a subscriber to the Flying Frisby.Until next time,Dominic This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit www.theflyingfrisby.com/subscribe